

So in almost 3 years of no blog post (I mean real writing, not the last post commemorating our 7th year anniversary), my writing juices finally started flowing and guess what, it is not about travel, nor health, nor dining/food, but a rare insight into one of my passions: finance. Yeah, may sound boring to most people, but stay with me and I will make it interesting particularly to those who are into investing. It is not really a pivot from the lifestyle blogs that I have posted in the past, because one can only support a lifestyle if you know how to manage your own finances (unless you are a nepo baby who can maintain a lifestyle out of a benefactor). Given the recent entry of Mynt (GCash) that shook the Philippine stock market from its deep sleep (well I guess the initial jolt was short-lived coz it went straight back to sleep), I thought it may be a perfect vehicle for me to give my two cents and for you to gain access to my brain,
You may ask how can I be credible to provide my take on the biggest initial public offering (IPO) in Philippine stock market history. Well, you may already know that I am a finance professional who works to travel (as my profile suggests), but what you may not know is that I have decades of professional experience supporting close to 50 markets in Europe, Middle East, Africa, Asia Pacific, and Americas where my last assignment was being the first foreigner to lead a specialized area of finance under institutional clients group (where big institutions like Mynt and its foreign cornerstone investors and bookrunners belong) that covers positions, risks, and profitability of capital market products. I have worked and lived in 5 countries (including the Philippines where I am a Certified Public Accountant) and because I work to travel, I have been to 34 countries (and counting) in 6 continents. So my perspective and education are broader not only due to my travels, but also from my professional finance experience, working with people in global financial hubs (New York, London, Tokyo, Hong Kong, and Singapore) as well as with finance and market professionals in all those 50 countries.
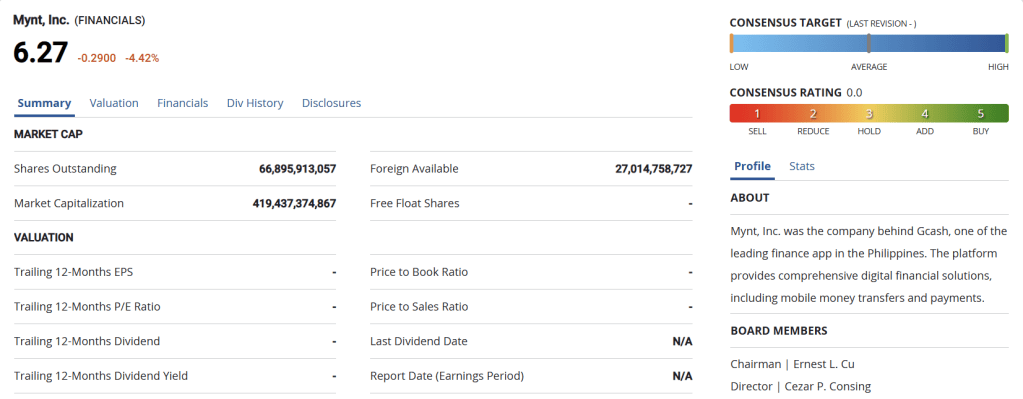
Now that I have convinced you that I am totally legit (I hope lol), let’s get back to Mynt IPO. GCash is the most popular finance tech app in the Philippines and arguably the pioneer (first entrant), used by about 94 million (out of 115 million) Filipinos to transfer cash and borrow money (lending). Gone were the days where one would go to 7-11 stores to send money or go to the neighborhood pawnshop to borrow money. Filipinos have done both in the app since its introduction in 2004, that’s why it has been ingrained in the Filipino way of life. So one would expect that the GCash IPO would be a blockbuster from the get-go, given that Filipinos would surely troop to get their hands on the stock, and it surely did. A lot of brokers have reported multiple times oversubscription and it comes as no surprise given the popularity of GCash among institutional investors (foreign and local) and accessibility to retail investors (anyone who has the app came with auto shares allotment).
So why wasn’t I jumping on the bandwagon? Why wasn’t I getting in on the action? I should admit that there was interest initially until I started looking around (also true in a relationship where attraction comes first, then reality takes over). The attraction was at 6.60 pesos per share, it looks cheap compared to the cap of 10 pesos that Mynt initially set. So there was a potential 33% gain to be made a piece, which under this stock market, is very lucrative. If I have a hundred thousand IPO shares and the price shoots up to 10 pesos, I would realize a 330,000 pesos gain which is already good for a Europe trip (on business class even with today’s fuel surcharges). Sounds enticing, right? Not only that, the cornerstone investors who set the price at 6.60 pesos look like the who’s who of the capital markets world where two of the biggest names are BlackRock, Inc. (one of the biggest fund managers in the world, including its iShares exchange traded fund or ETF for MSCI Philippines) and International Finance Corporation (duh, World Bank). Its IPO bookrunners are also the biggest investment banks in the world, with names like UBS and JP Morgan to name a few. So nothing in a Filipino wildest dream could go wrong, right? Right?? RIGHT???
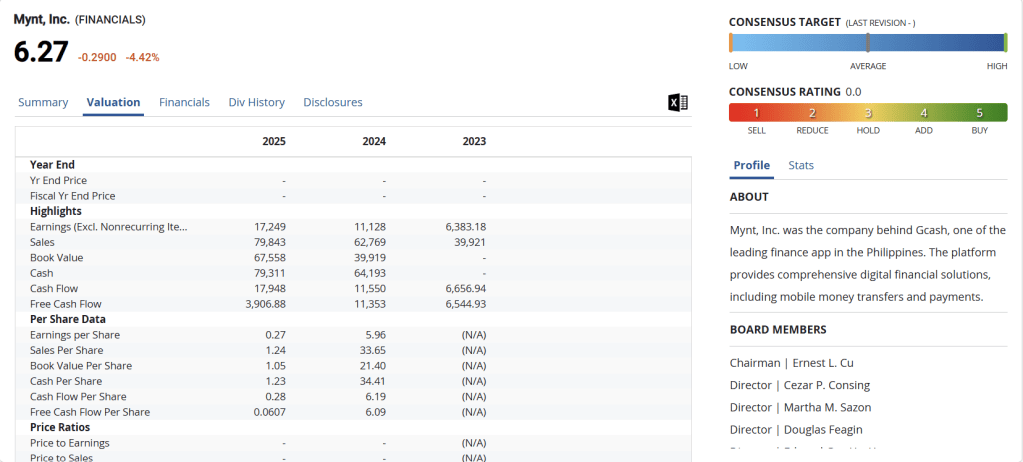
Hmm, in a perfect world, yes. But we don’t live in a perfect world. In investing world (and in any other alternate universe or multiverse), red flags exist. Just like in a relationship, you have to look for red flags. In Mynt’s case, the 6.60 pesos price is not cheap. It’s very expensive. How expensive? Take a look at its earnings per share (EPS). At 0.27 pesos EPS (as of end of 2025), a 6.60 pesos price is 24.4x Price/Earning ratio (P/E). It means the price is 24.4x more than its earnings. In layman’s terms, if you pay at that price, you are expecting the company to generate earnings 24.4x its current earnings in say 10 years. Is that possible? Maybe, but if you look for big, blue chip companies that have that same or similar P/Es, you’ll only see ICTSI (a Filipino company like Mynt and one of the biggest ports operators in the world) that has that P/E and not only has the biggest market capitalization in the Philippine Stock Exchange Index (PSEi) but also has established a track record and the current darling of the index. Mynt, on the other hand, is just a newbie, and compared to the P/Es of the biggest listed traditional banks in the Philippines such as BDO and BPI where the current P/Es are 7.15x and 7.73x respectively, then you will start to think whether Mynt’s earlier phenomenal growth is sustainable. The fact that the growth is cooling already makes you doubt it. Then you have the composition of the IPO. About 80% of it would come from secondary shares (or shares which proceeds from IPO would go to existing shareholders such as Globe, Ayala Corporation, and directors, officers, and employees of Mynt and these companies to name a few) and only 20% are primary shares (or shares which proceeds from IPO would go to growing the business, pay its loans, etc.). Optics wise, it doesn’t look good coz not only will someone receive a huge payday from the IPO, but only a small part of the proceeds will actually be put to good use to achieve that 24.4x earnings in the next several years. If I want to buy secondary shares, I would rather look at companies that are already listed in the index with proven track record (earnings and dividends wise) and are currently very cheap (like BDO or BPI for example).
Then here’s the clincher: the credit risk. GCash non-performing loans (NPL) is currently at 4.9% if I am not mistaken (correct me if I am wrong). Compare to BDO’s 1.8% and BPI’s 2.1% (again, correct me if I am wrong), 4.9% seems to be too high but not surprising at all. GCash debtors are generally people who need the cash to buy stuff and do not really share the same customer profile as those with traditional banks. Just to give you an idea of how much is the impact of NPL in a bank’s earnings, in 2025, BPI provided 17.75 billion pesos for loan loss while BDO provided 15.01 billion pesos for the same. Metrobank (MBT), which is the listed traditional bank that is closest to Mynt in terms of market capitalization (276 billion pesos compared to Mynt’s 419 billion pesos), has provided 11.92 billion pesos for loan loss. So imagine what provision for loan loss would look like for Mynt from a 4.9% NPL perspective. Given that the lending business is currently Mynt’s main driver for growth, how much investors’ appetite for credit risk will determine risk-growth trade-off (giving up a bit of your risk aversion for faster growth or keeping a bit of your risk aversion for moderate growth). How much credit risk appetite will also determine whether the 24.4x earnings is achievable or just another bubble waiting to burst, when reality takes over.
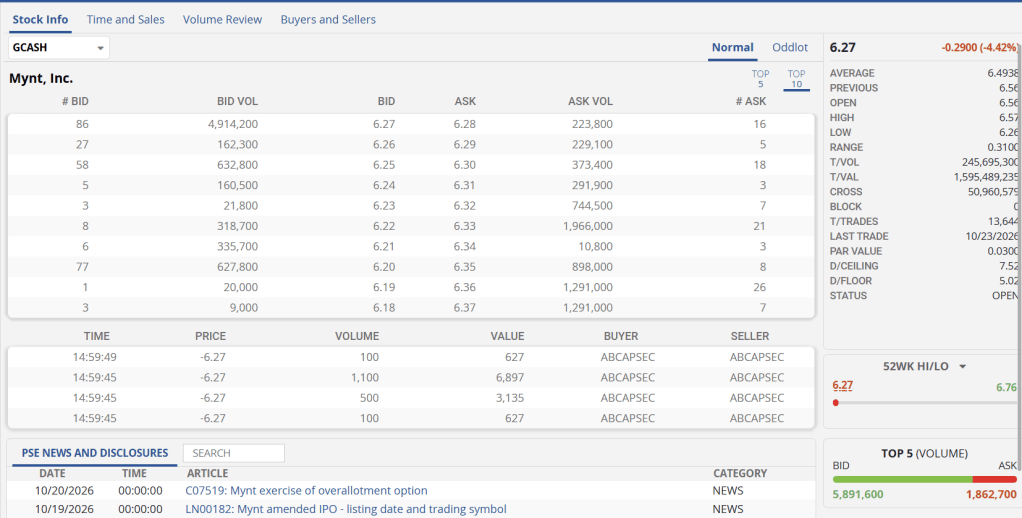
Mynt shares ended the week (October 23, 2026) at 6.27 pesos, or 5% lower from its IPO price, 3 days after its listing in the index. The highest price was at 6.76 pesos during intraday trading on October 20 (IPO date), or a 2.4% gain if you were among the very few who were able to sell at that price. Some of you may be asking if there is any chance for the price to go up. Well, I don’t have a crystal ball, but the signs are not really in that direction right now given that its bookrunner, UBS, has been buying the shares to stabilize the price. This is similar to the last biggest IPO, Monde Nissin, where the price also went down and UBS kept buying to stabilize the price, but then broke past its IPO price and reached an all-time high of 53.3% three months later. Not saying that this will also happen to Mynt (two entirely different business models) but who knows, maybe after its earnings report in the coming weeks will shed more light on how its price will go.
Why the IPO was bad is not because the price has gone down. It was bad because the IPO price did not factor in the red flags. The fact that Mynt’s minimum indicative price was initially set at 7.50 pesos (until the cornerstone investors lowered it to 6.60 pesos) and maximum indicative price at 10 pesos, something was already off (or maybe they were just too optimistic of their earnings growth potential). Not to throw shade on Mynt (I still believe it has a very innovative business model and a sound company, at least at this point), but if the pricing was more realistic (a price that would reflect what it really was, a liquidity-making opportunity for its pre-IPO investors), it would have been the blockbuster that they wanted it to be. They don’t have to send out a press release post-IPO to tell investors to wait for its next earnings report. That just confirmed what I knew all along, that something was really off.
So what did we learn from this IPO? The saying “too good to be true” applies here, as well as in everything else. Always have a discerning mind and scrutinize every press release or mainstream media news that may inadvertently mislead an unsuspecting reader (just like the headline news where they attributed the rise in PSEi on October 20 market close to Mynt’s IPO when GCash is not even part of the basket of 30 blue chip companies that comprise the index). A 5% loss may not be that bad, but if you’re someone who was hoping to receive a windfall on IPO date when you bought that stock (after all the effort and fighting to get a bigger share allocation), then I guess you now have the realization on who actually had a windfall and who ended up paying for it. Yes, new billionaires were made on this listing, but that doesn’t make it a good IPO, right? Right?? RIGHT???


